How to Evaluate 485 Liberty Mutual Pet Insurance Before You Buy
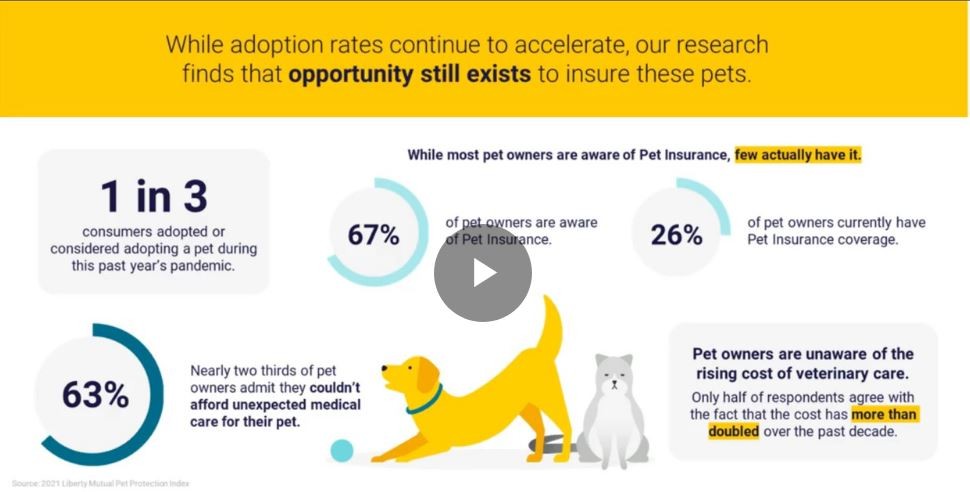
Pet insurance is a reimbursement product, not a prepaid vet card, and the difference matters most when you are standing at a clinic counter with an estimate in hand. 485 liberty mutual pet insurance is a familiar name in home and auto coverage, but its pet insurance is not underwritten by Liberty Mutual itself in every market. In the United States, the coverage is offered through a partnership with a licensed pet insurance provider, and in Australia it is issued by Pet Insurance Australia. That structure shapes everything from who answers your claim questions to whether your existing agent can help. This guide focuses on the practical buying decisions: what to compare, what to ask, and what to expect when you file.
Confirm Who Actually Insures and Services the Policy
Before you enter payment details, identify the actual underwriter and administrator. In the U.S., Liberty Mutual pet policies are administered by a partner insurer; in Australia, Pet Insurance Australia issues the policy. This matters because claims, medical record reviews, and customer service are handled by that partner, not by Liberty Mutual’s core home and auto teams.
Ask these questions before buying:
- Who is the underwriter named on the certificate of insurance?
- Can I manage the pet policy inside my existing Liberty Mutual account, or is there a separate portal and app?
- Can my current Liberty Mutual agent answer pet policy questions, or will I be transferred?
- Which regulator supervises the insurer in my state or territory?
If you already bundle home or auto coverage, do not assume the pet policy will appear on the same dashboard. Confirm the claims channel and download the app before your pet needs care, not during an emergency.
Compare Coverage Types, Limits, and Reimbursement Math
Most pet insurers, including Liberty Mutual’s partner-issued plans, offer two core structures: accident and illness plans, and accident-only plans. Accident and illness plans typically cover emergency visits, illnesses such as cancer or infections, hereditary and congenital conditions depending on the policy, diagnostics like X-rays and blood work, surgeries, hospitalization, and prescription medications. Accident-only plans generally cover injuries such as bite wounds, fractures, or toxic ingestion but exclude illnesses. Routine care such as vaccinations, annual exams, and flea and tick prevention is usually excluded unless a wellness rider is available.
Three numbers control your payout:
- Deductible: Your out-of-pocket amount before reimbursement begins. Annual deductibles are common; per-condition deductibles also exist.
- Reimbursement rate: The percentage of eligible costs paid after the deductible. Common options are 70%, 80%, and 90%.
- Annual limit: The maximum the insurer pays per year. Limits may be $5,000, $10,000, or unlimited depending on the plan.
Run a worst-case estimate yourself. If a $6,000 surgery meets a $500 annual deductible at 80% reimbursement, the insurer pays 80% of $5,500, or $4,400, leaving you $1,600 plus any excluded costs. At 90%, you would owe $1,050 plus exclusions. That gap is the real price of the lower reimbursement rate.
Understand Waiting Periods, Pre-Existing Conditions, and Exclusions
No pet insurance policy covers pre-existing conditions. A condition counts as pre-existing if it showed signs or symptoms before coverage started or during the waiting period, which is why insuring a young, healthy pet usually produces the best outcome. Typical waiting periods run a few days for accidents and roughly two to four weeks for illnesses, with longer waits, sometimes six months, for cruciate ligament conditions.
Expect exclusions for pre-existing conditions, routine care without a wellness add-on, cosmetic or elective procedures, breeding and pregnancy, experimental treatments, and dental disease unless dental illness coverage is added. Some policies also cap payouts for specific conditions such as cruciate ligament repairs.
Read the policy disclosure statement or certificate of insurance line by line. If a breed-specific risk, such as dental disease in small breeds or hip issues in larger dogs, is a dealbreaker, ask whether a rider exists and what it costs. Keep every vet record from day one; documentation is how you prove a condition was not pre-existing.
Check Discounts, Sizing Your Budget, and Return Policies
Multi-pet discounts may apply when you insure two or more pets on the same policy, and in Australia a multi-pet discount is commonly offered. In the United States, because the pet coverage is administered by a partner, bundling with Liberty Mutual home or auto may not automatically reduce the pet premium, so ask directly rather than assuming.
Sizing your policy is like sizing a garment: the fit matters more than the label. A young, healthy pet with a solid emergency fund may suit a higher deductible and 80% reimbursement. An older pet or a breed prone to hereditary conditions may justify a lower deductible and a higher annual limit, even at a higher monthly premium. Compare at least two standalone insurers against the Liberty Mutual partner plan on base premium, annual limit, and claims processing speed.
Return and cancellation rules vary by provider and by state or territory. Most policies offer a free-look window, often 14 to 30 days, during which you can cancel for a full refund if no claims have been filed. After that window, cancellations are typically pro-rated or effective at the end of the paid term. Ask about the free-look period, the refund method, and whether cancellation fees apply before you enroll.
Claims, Photography, and Venue Considerations for Faster Reimbursement
The claims process is reimbursement-based: you pay the vet in full, then submit a claim online or through the app, usually within a set window such as 90 days. You are generally not restricted to a network, so any licensed veterinarian works. Provide itemized invoices and medical records when requested, and expect direct deposit or a check after assessment.
Clear documentation speeds everything up:
- Photograph the full invoice on a flat, well-lit surface, keeping all line items and totals in frame.
- Capture diagnosis codes and treatment dates; ask the clinic to include them if missing.
- Scan or photograph medical records as PDFs or high-resolution images, not blurry phone snaps.
- Store everything in a dated digital folder so you can resubmit if a claim is questioned.
Venue also matters. Emergency hospitals often require payment at discharge, so confirm whether the clinic offers payment plans or accepts care credit before treatment. If you travel with your pet across state or national borders, check whether the policy covers treatment outside your home region and how claims are submitted from abroad.
Making the Final Decision
Liberty Mutual pet insurance can work well if you value brand familiarity and are comfortable with a partner-administered, reimbursement-based policy. The coverage tiers are broadly competitive, and multi-pet discounts may help. But the brand name alone is not a reason to buy. Verify the underwriter, confirm the claims channel, model your worst-case costs, and check the free-look and cancellation terms. Request a sample policy and compare it side by side with at least two other insurers on premium, annual limit, exclusions, and processing time. The best policy is the one that actually pays when your pet needs expensive care, and that is a decision you can only make with the certificate of insurance in front of you.



0 Comments